Independent advice Bad Oeynhausen استشارة بالعربية

Understand your health insurance. Before you sign it.

Private health insurance in Germany is the decision you make once and carry for forty years. I will explain it for as long as it takes. In German, English or Arabic.

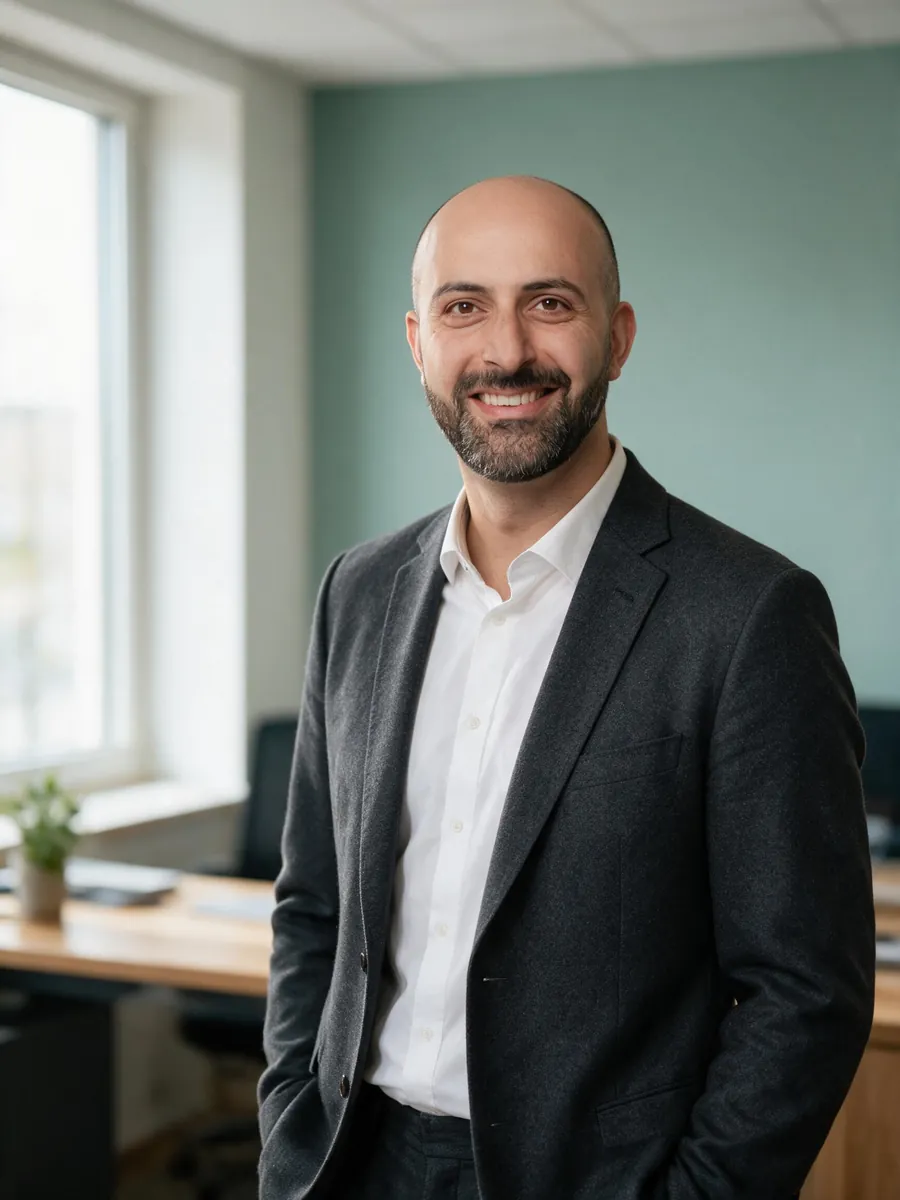
Mohamad Abdallah, portrait
Experience
20 years
Languages
Deutsch · English · العربية
First call
Free of charge
Reachable
Phone & office

Why it feels so hard

You are not the complicated part. The system is.

Eighty pages of terms. Twelve health questions. A decision that is close to irreversible. Hesitating is not a failure to understand — it is common sense.

Listen
Decide

Who I help

Four starting points, four completely different calculations.

You pay into a professional pension scheme rather than the state system — which leaves you in retirement without the contribution the state pension would otherwise pay towards your health insurance. Noticing that at 60 is expensive. Planning for it at 30 costs almost nothing.

Talk it through
No income threshold applies to you — private cover is open at any income. But you carry the full premium yourself. And the public system assesses your income retrospectively, which regularly produces unpleasant back-payments.

Talk it through

From a gross annual salary above €77,400 you have the choice in 2026. Your employer contributes to private cover too — half your premium, capped at €613.22 a month. Whether it pays off depends on your age, your health and your family plans.

Talk it through

This is where I say no most often. In the public system children and non-earning partners are covered at no extra cost — privately, every person needs their own contract. With three or four people the maths often flips.

Talk it through

The fundamental choice

Public or private — what the difference actually is.

There are good reasons for both. Private is not automatically better. What matters is your situation.

Read the decision guide

Public (GKV)

Right for most people
  • Premium based on income14.6 % plus a supplementary rate, capped at €5,812.50 gross a month. At most around €1,261 a month including long-term care insurance — that is the total premium, of which your employer carries roughly half.
  • Family covered for freeChildren and partners without their own income are included at no extra cost, up to €565 a month. Careful: if one parent is privately insured and is the higher earner, this no longer applies to the children.
  • No health assessmentPre-existing conditions are irrelevant. Nobody is turned down.
  • One standard benefit catalogueSet by law, identical for everyone. Longer waits for specialists.

Private (PKV)

My specialism
  • Premium based on age and healthNot on income. Entering young and healthy costs considerably less — and that effect compounds over decades.
  • One contract per personIncluding children and partners. This is the point where family calculations tip over.
  • Faster access to specialistsAppointments in days rather than weeks. Senior consultant and two-bed room depending on tariff.
  • Health assessment requiredPre-existing conditions lead to surcharges, exclusions or rejection. That is why we ask anonymously first.

About me

Twenty years inside a system nobody reads for pleasure.

More about me
Mohamad Abdallah im Beratungsgespräch an seinem Bürotisch

I have advised people on health insurance for twenty years. I started because I kept seeing the same scene around me: someone holding a German form that decides the next forty years of their life — and nobody to explain it in their own language. That is exactly what I do now. From my office in Bad Oeynhausen, for clients across Germany.

20years of professional experience
3languages: German, English, Arabic
“Advice you do not understand is not advice. It is a sale with better manners.”

Mohamad Abdallah

Auf Deutsch

Technical terms explained rather than assumed. Even if German is not your first language.

In English

The whole conversation, the forms, the follow-up. Nothing gets lost because of language.

بالعربية

شرح كامل بلغتك الأم، من أول مكالمة حتى توقيع العقد وما بعده.

Real numbers

What does someone on €80,000 gross pay?

Sample case: 35 years old, employed, no children, healthy. All figures are monthly amounts for 2026.

Item
Public
Private, solid
Private, comprehensive
Health insurance
1.017,19 €
approx. €350–450
approx. €500–650
Long-term care insurance
244,13 €
approx. €50–60
approx. €50–60
Total premium
1.261,32 €
approx. €400–510
approx. €550–710
Employer contribution
−613,22 €
approx. −€200–255
approx. −€275–355
Your share
648,10 €
approx. €200–255
approx. €275–355

The public figures are based on the official 2026 parameters: contribution ceiling €5,812.50 a month, rate 14.6 % plus the 2.9 % average supplementary rate — your own fund may charge more — long-term care insurance 3.6 % plus the 0.6 % childless surcharge, employer contribution capped at €613.22. The private figures are ranges, not quotes; your actual premium depends on the outcome of the health assessment. Which is precisely why I ask insurers anonymously first, instead of promising you a number here. Different rates apply in Saxony. Individual amounts are rounded.

In a hurry? Just call.

An appointment at the immigration office, an employer waiting for proof, a rejected application. These are not special cases, they are everyday work. You get a reliable answer on the same working day.

Common questions

What people ask me most.

Ask your question

Employees whose gross annual salary exceeds €77,400 — that is the income threshold for 2026. Important: if you cross that line through a pay rise, you cannot switch immediately, only from the end of the calendar year. If you start a new job already above it, you can switch straight away. Self-employed people and freelancers can switch regardless of income, as can civil servants and students at the start of their studies. For doctors, the professional pension scheme adds another set of rules.

No. I am paid by the insurer you eventually sign with — not by you. The first conversation is free and commits you to nothing. And if private cover would be the wrong decision for you, I will say so, even though I then earn nothing.

As an employee, if your income falls back below the threshold then in force — through part-time work, parental leave or unemployment, for instance. From the age of 55 it becomes practically impossible: § 6 (3a) SGB V bars the return if you have been outside the public system for five years and were exempt from compulsory insurance or self-employed for at least half of that time. This is the most underestimated point in the whole system — and the reason this decision deserves honest advice.

As a rule, no. The assessment runs through a written questionnaire on pre-existing conditions, medication and treatments over recent years. What matters is answering it fully and truthfully — incorrect answers can still bring down the contract years later. Beforehand I make anonymous enquiries with several insurers, so that a rejection never reaches your record in the first place.

No — and this is the most important difference from the public system. Privately, every family member needs their own contract with their own premium. For children that is typically €100 to €180 a month in our experience. For larger families with one non-earning parent the public system is therefore often cheaper. I will calculate both before you commit.

Your contract goes dormant through a so-called Anwartschaft. Your accumulated ageing provisions and your health rating at the start of the contract are preserved — you return without a new health assessment. This should be arranged before you leave, not afterwards.

In a straightforward case the contract is usually in place within three to five working days. Note the waiting periods, if your tariff has any: the law caps them at three months in general and eight months for dental treatment, dental prosthetics, orthodontics, psychotherapy and childbirth. They do not apply to accidents, and if you are coming straight from previous cover they are normally credited. Some tariffs waive them entirely. If you need proof for the immigration office or an employer, say so in the first conversation — there are ways.

Contact

Write to me. Or simply call.

You reach me personally — no call centre, no queue. Usually an answer on the same working day.

Direct

Phone05731 4999031 Mobile0175 3434344
OfficeDehmer Str. 27 A
32549 Bad Oeynhausen

Advice in German, English and Arabic — just tell me which is easier for you.

Please enter your name.
Please leave a way to reach you.
Age, occupation, rough gross income and your question are plenty to start with. Please describe your enquiry briefly.
Without this consent we are not allowed to process your enquiry.
Your enquiry has arrived.

I usually come back to you on the same working day. If it is urgent, feel free to call directly.

WhatsApp
Send enquiry Call